By the Resource Erectors Research Team
For heavy civil contractors, quarry operators, mining conglomerates, and ready-mix concrete producers, diesel fuel is not an abstract commodity ticker. It is the lifeblood of the physical economy.
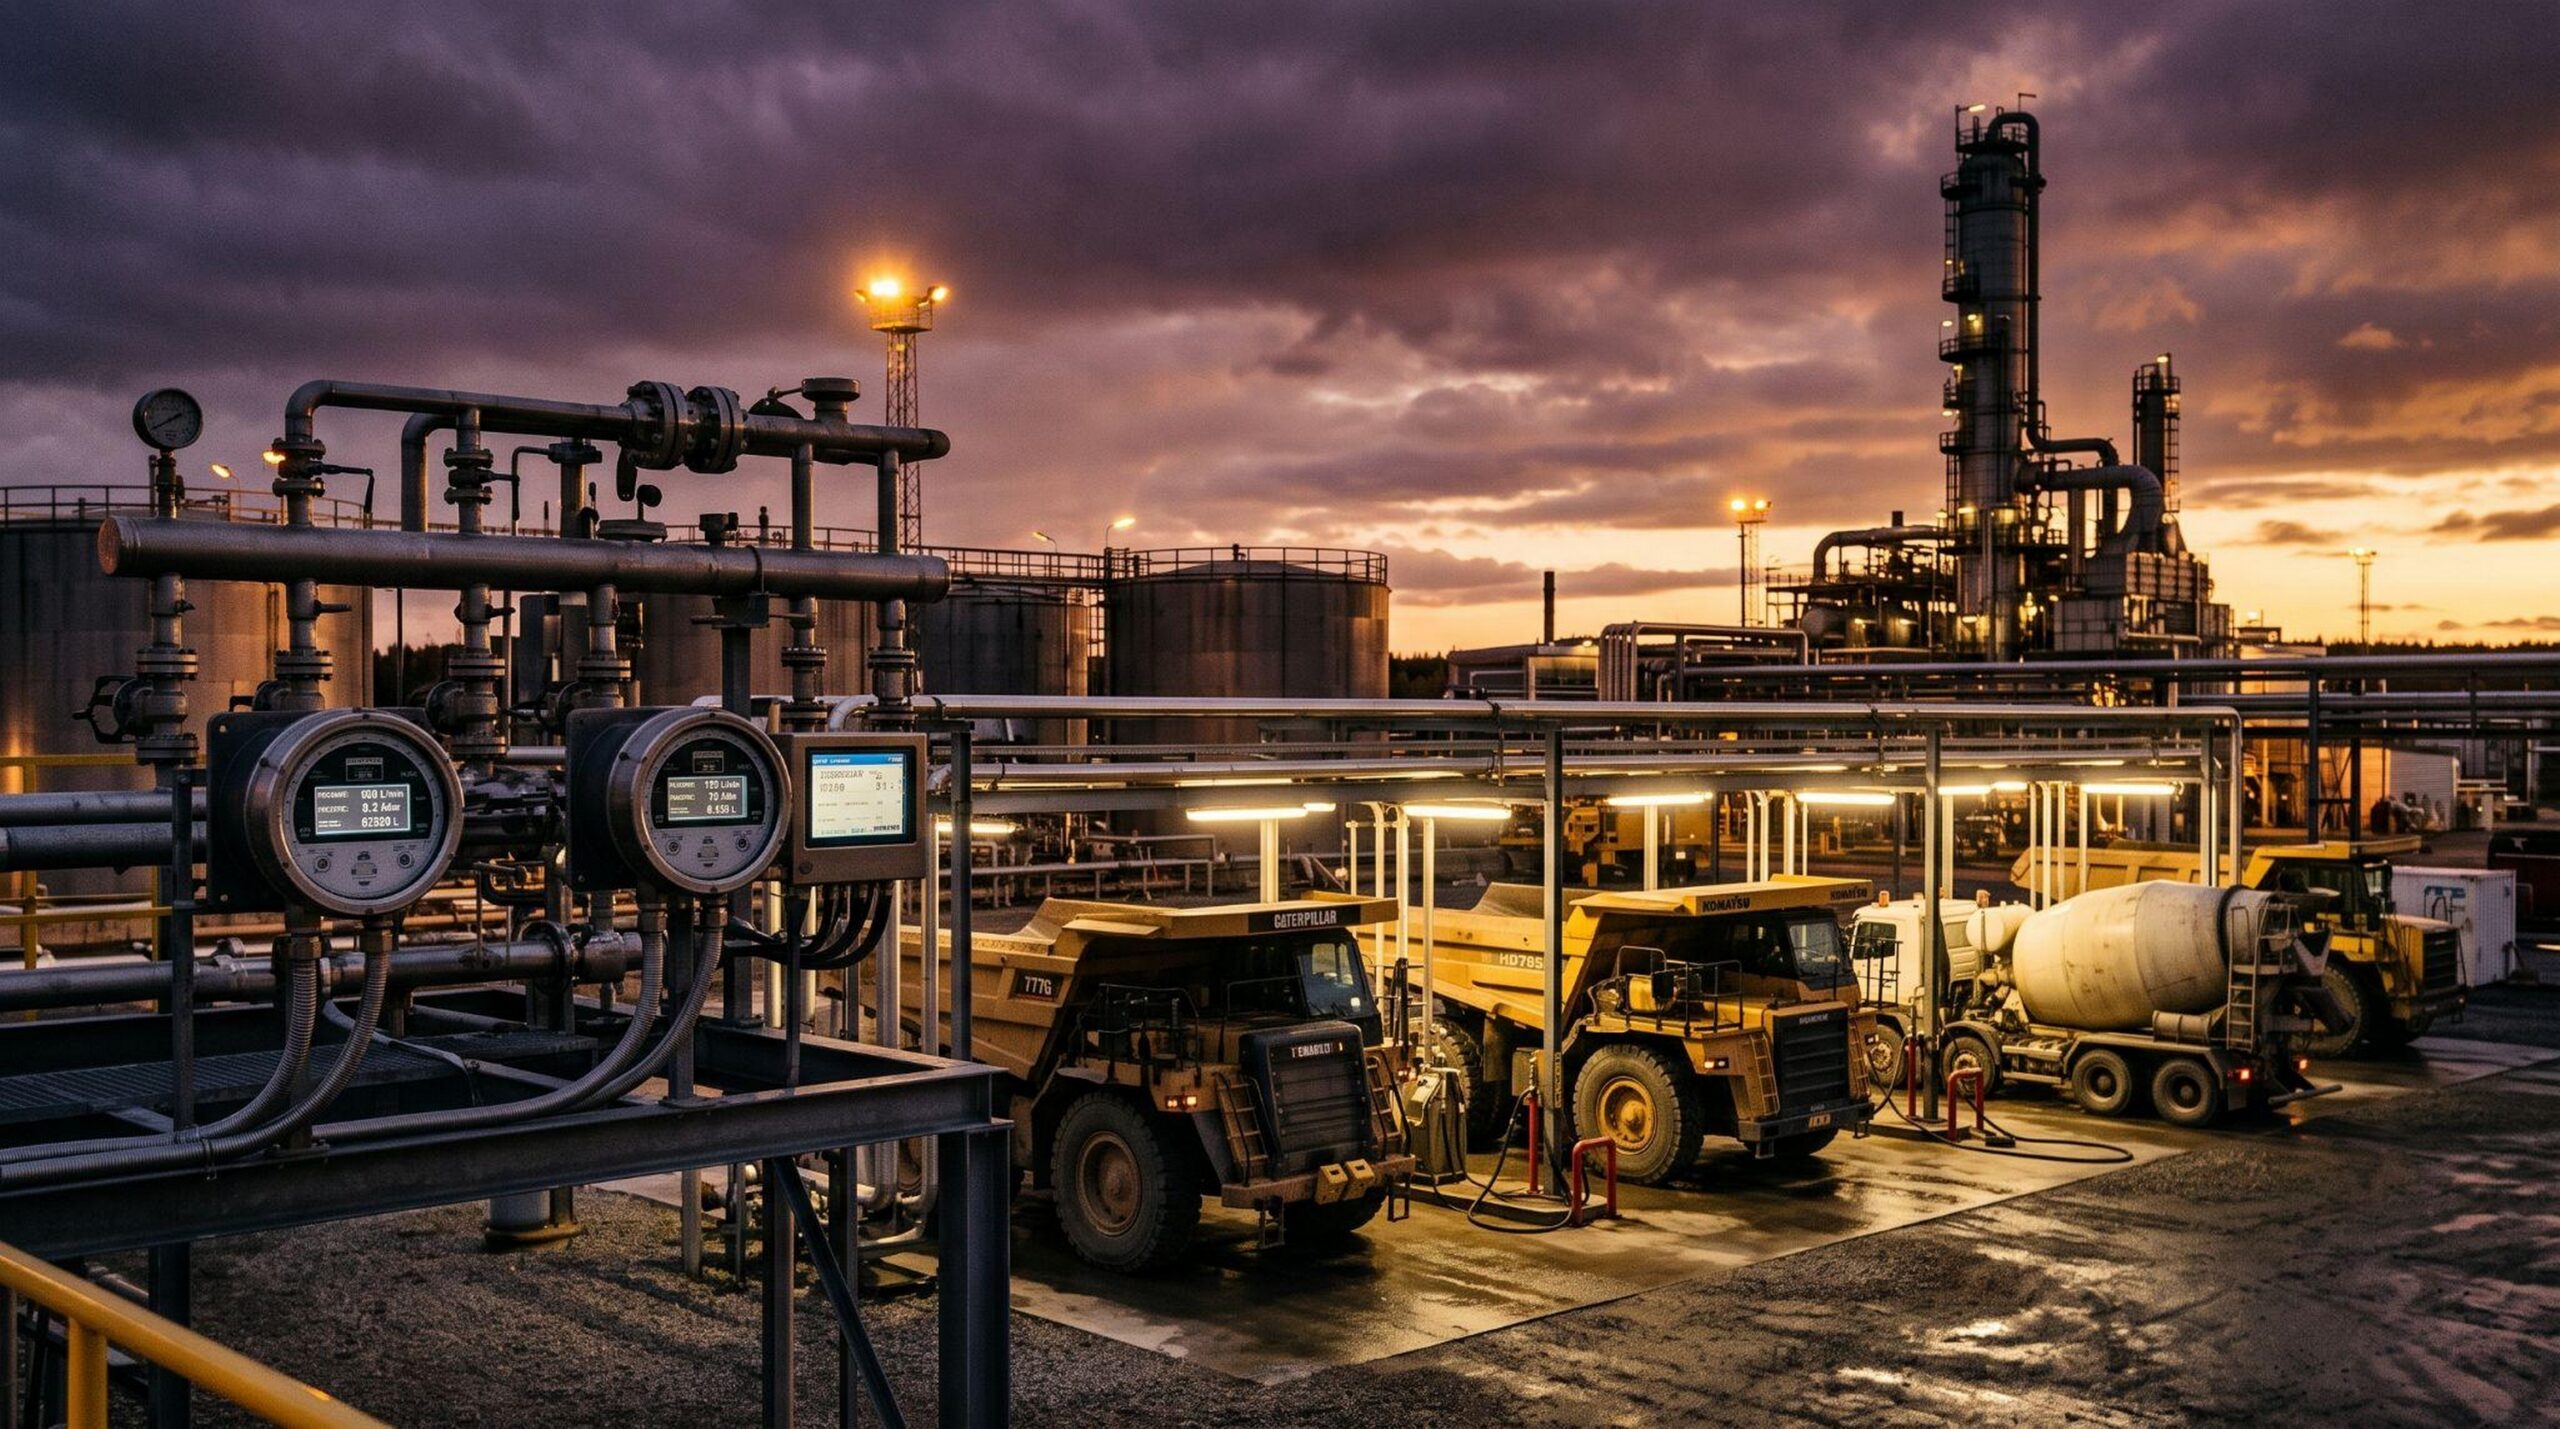
Whether powering a 100-ton haul truck climbing out of an aggregate pit, running auxiliary hydraulic power units on a continuous milling machine, or turning transit mixer drums through metropolitan traffic, diesel represents one of the largest variable cost line items on any producer’s profit and loss statement.
Yet as industry rolls toward the fourth quarter of 2026, fleet directors and operations executives face a volatile pricing landscape. Diesel prices are no longer dictated simply by domestic supply and demand or seasonal shifts.
Instead, industrial operators find themselves caught in a structural squeeze. On one side are geopolitical fires across critical energy corridors in Eastern Europe and the Middle East. On the other lies a fundamental chemical and engineering mismatch: America is pumping record volumes of light crude from shale basins, but our refining complex lacks the processing chemistry to turn that flood of light tight oil into heavy distillate diesel.
Understanding these converging forces is essential for operations leaders managing high-volume fuel allocations, negotiating customer delivery surcharges, and protecting operating margins through the final quarter of the year.
The Global Flashpoints: Drone Attrition and Chokepoint Risk
Crude oil and distillate markets are operating on a razor-thin margin of error as 2026 draws to a close. Two major international conflicts continue to disrupt global petroleum flows, injecting high-beta volatility directly into wholesale diesel racks.
The Black Sea and Russian Refining Attrition
Throughout 2026, the Russia-Ukraine conflict has shifted into a grinding air war targeting downstream petroleum infrastructure. Ukrainian long-range drone strikes have repeatedly struck primary distillation towers, vacuum columns, and catalytic crackers across European Russia.
- Lost Processing Capacity: Sustained strikes have removed over a million barrels per day of Russian refining capacity from operation, knocking out roughly 15% to 20% of the country’s domestic diesel manufacturing capability at key intervals.
- Export Restrictions: Historically one of the world’s primary exporters of seaborne diesel and gasoil, Russia has been forced to impose emergency export restrictions to protect its internal agricultural and military supplies.
- European Distillate Deficits: With Russian refined barrels largely absent from European supply chains, Atlantic Basin buyers have had to bid aggressively for replacement cargoes from the U.S. Gulf Coast, India, and the Middle East, pulling North American export barrels away from domestic shores and establishing an elevated global price floor under diesel.
The Persian Gulf and the Strait of Hormuz Chokepoint
Concurrently, simmering tensions between the United States, Israel, and Iran continue to cast a shadow over the Persian Gulf. The 21-mile-wide Strait of Hormuz remains the single most critical transit artery in global energy, with roughly 20% of the world’s petroleum consumption passing through its shipping lanes.
- Maritime War-Risk Premiums: Recurring seizures, drone harassment, and tanker boarding operations have forced commercial marine insurers to impose steep war-risk surcharges on Very Large Crude Carriers (VLCCs) transiting the Gulf of Oman.
- Sanctions Friction: Tighter enforcement of sanctions on Iranian crude export networks has restricted the availability of heavy, sour barrels moving into Asian merchant refineries, forcing overseas buyers to seek alternative crude grades on the open market.
- Asymmetric Threat to Middle Eastern Megaprojects: Any escalatory flare-up threatens not only raw crude transit, but also the massive new export-oriented export refineries commissioned across the Gulf, leaving international distillate supplies acutely vulnerable to sudden logistical cutoffs.
The Chemical Mismatch: Why More Frack Oil Doesn’t Mean Cheaper Diesel
The most misunderstood aspect of the domestic diesel market is the persistent claim that record U.S. oil production should automatically yield an ocean of cheap diesel fuel.
The United States is producing historic volumes of crude oil, driven primarily by hydraulic fracturing across the Permian, Bakken, and Eagle Ford formations. However, crude oil is not a monolithic fluid. Its chemical composition dictates what a refinery can physically produce from it.
The Chemistry of Light Tight Oil (LTO)
Crude oil from shale fracking is classified as Light Tight Oil (LTO)—an ultra-light, sweet crude with an API gravity frequently exceeding 40° to 50°.
When LTO enters an atmospheric distillation column:
- Flooded with Light Ends: Light shale crude is heavily concentrated in short-chain hydrocarbons. It yields massive percentages of natural gas liquids (ethane, propane, butane), light naphtha, and gasoline blending components.
- Deficient in Middle Distillates: Light crude naturally contains a much smaller percentage of the long-chain, dense hydrocarbon molecules required to produce middle distillates: No. 2 diesel fuel, jet fuel, and heating oil. A barrel of light frack crude typically yields only 20% to 25% diesel, compared to 35% to 40% or more from traditional medium and heavy crudes.
The Legacy Gulf Coast Refining Architecture
During the 1990s and 2000s—long before the shale revolution unlocked domestic tight formations—American refining companies invested tens of billions of dollars reconfiguring Gulf Coast refineries to process cheap, heavy, high-sulfur (sour) crudes imported from Canada, Mexico, Venezuela, and the Middle East.
These facilities were engineered with massive coking units, vacuum distillation columns, and deep hydrocrackers designed to crack thick, heavy residual oils down into high-value diesel and gasoline.
When a complex refinery attempts to run exclusively on light frack oil:
- Distillation Bottlenecks: The light-ends processing units become overwhelmed by excess naphtha and light gases, forcing the refinery to slow down overall crude intake.
- Starved Secondary Conversion Units: The multi-billion-dollar cokers and hydrocrackers sit underutilized because light shale oil contains almost no heavy residual “bottoms” to feed them.
- The Technology Deficit: There is currently no commercially viable, scalable secondary refining technology that can economically recombine light naphtha molecules into heavy distillate diesel molecules without astronomical capital expenditure and high carbon intensity.
To run at peak efficiency and maximize diesel output, American refiners must continually blend light domestic shale oil with imported heavy sour barrels—largely from Canadian oil sands via rail and pipeline, or maritime shipments from Latin America. When global supply chains for heavy crude constrict due to geopolitical conflict, domestic refiners cannot simply replace those heavy molecules with domestic frack oil to produce more diesel.
The Seasonal Collision: The Q4 Operational Squeeze
This structural refining bottleneck collides directly with four cyclical market drivers that hit the downstream supply chain every autumn:
- The Distillate Tug-of-War: Diesel and home heating oil are chemically near-identical No. 2 fuel oils. When late-autumn cold fronts sweep through the Northeast and Upper Midwest, residential and commercial heating systems pull hundreds of millions of gallons of distillate out of transportation channels. Because heating demand is completely inelastic, supply tightens instantly.
- Autumn Refinery Maintenance (Turnarounds): Following the high-throughput summer driving season, refineries across the Gulf Coast and Midwest enter scheduled autumn maintenance, taking critical fluid catalytic crackers and hydrotreaters offline for mechanical overhauls. This reduces total finished distillate production precisely when agricultural and heating demand peaks.
- Agricultural Harvest Surge: Between late September and November, thousands of combines, tractors, and Class 8 grain haulers run continuous shifts across the Midwest to bring in the annual harvest, driving sharp, localized demand spikes at regional fuel distribution racks.
- The Winter-Blend Premium: As freezing temperatures approach, fuel terminals transition to winterized diesel, blending in specialized cold-flow improvers and higher percentages of No. 1 diesel (kerosene) to prevent fuel gelling and wax crystallization. Kerosene is costlier to refine, adding a direct premium to rack wholesale costs.
Conversely, late Q4 can also trigger sudden, temporary price drops. Once northern construction projects shut down for the freeze, agricultural harvests conclude, and refineries complete their turnarounds in December, fuel distributors often discount spot barrels to empty storage tanks before year-end property taxes take effect.
Fleet Strategy: Protecting Margins in an Era of Volatility
Given the structural realities of the global oil market and the physical limitations of domestic refining, relying on retail spot pricing or static annual fuel allowances is a recipe for margin erosion.
Operational leaders across heavy civil, aggregates, and mining operations protect profitability by deploying proven commercial strategies:
- Dynamic, Index-Linked Fuel Surcharges: Structuring customer supply agreements with transparent fuel surcharge formulas tied to weekly Department of Energy (DOE) regional diesel benchmarks ensures that sudden rack spikes are passed through without eating operating profits.
- Bulk On-Site Storage Infrastructure: Maintaining permitted 10,000- to 20,000-gallon on-site fuel farms gives producers the purchasing leverage to buy transport-load bulk fuel during late-summer or late-December dips, bypassing retail rack volatility.
- Rigorous Telematics and Idle-Time Elimination: Modern fleet telematics platforms provide real-time visibility into non-productive equipment idling. In aggregate quarries and civil earthmoving sites, unmonitored idling can account for up to 30% of total diesel burn. Enforcing automated shut-off policies translates directly to balance-sheet defense.
- Proactive Fuel Chemistry Management: Implementing automated tank maintenance protocols—including regular filtration, biocide treatment, and moisture elimination—prevents water accumulation and microbial growth that destroy high-pressure common rail (HPCR) fuel injectors, avoiding costly downtime during peak operating schedules.
Understanding the deep connection between energy efficiency, emissions hardware, and operating costs is fundamental to modern fleet management, reflecting the operational priorities we examined in saving diesel fuel while reducing emissions through advanced engineering.
The Executive Leadership Imperative
Navigating the intersection of geopolitical turmoil, refining chemistry, and heavy equipment logistics requires more than tactical mechanical skills. It demands executive leadership that can manage supply chain risk, hedge procurement costs, and drive rigorous operational discipline across the field.
As heavy industry producers prepare capital budgets and operating plans for the coming year, placing forward-thinking general managers, equipment superintendents, and operations directors on the ground remains the definitive difference between chronic margin compression and sustained profitability.
Ready to Elevate Your Operational Command?
The heavy civil construction, aggregates, mining, and concrete sectors are demanding a higher tier of executive and technical leadership to navigate today’s volatile operating environment.
Whether you are a proven operations executive ready for your next career move or a heavy industry producer seeking top-tier leadership to safeguard profitability, Resource Erectors is your confidential recruitment partner.
Take control of your trajectory. Browse active career openings on the Resource Erectors job board or submit your resume for general consideration to connect directly and confidentially with CEO Dan Duszynski.
Time to Call Resource Erectors
At Resource Erectors, we specialize in connecting heavy industry producers with the elite leadership talent that drives operational excellence.
- For Employers: When your organization needs vetted Operations Directors, Fleet Maintenance Executives, or General Managers to protect margins, explore our specialized client recruitment services.
- For Professionals: When you are ready to make a strategic, confidential executive move to a premier heavy industry producer, visit our contact page today.